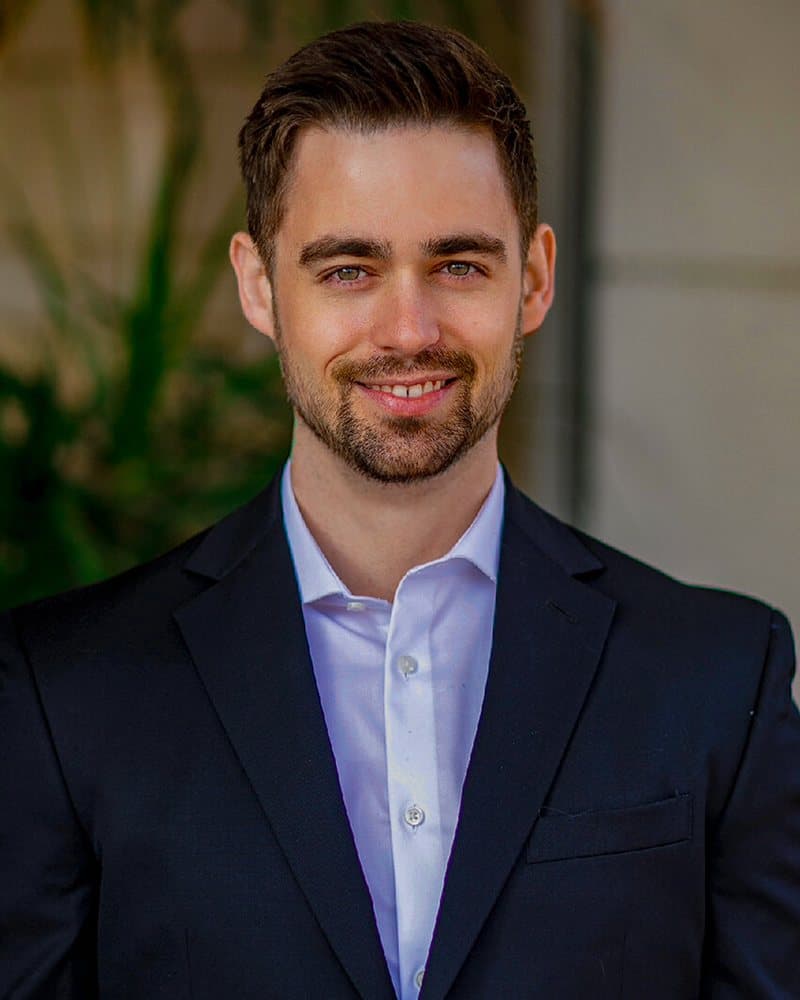
Zac Cook
Mortgage Loan Originator · NMLS #2111496(opens in a new tab)
Cornerstone First Mortgage, LLC · NMLS #173855(opens in a new tab)
About Zac
Zac Cook is a mortgage loan originator (NMLS #2111496) at Cornerstone First Mortgage, LLC (NMLS #173855) and, with his brother Tanner Cook, part of the Cook Brothers Mortgage Team. He focuses on asset-based, ITIN and foreign national loans for entrepreneurs, investors and international buyers.
Zac works with entrepreneurs, investors, and international buyers. He checks every file against the non-QM programs Cornerstone can offer in the borrower’s state, looking for a guideline that fits — from asset-based qualification to ITIN and foreign national programs.
Specialties
- Business Owner Mortgages
- Asset-Based Qualification
- ITIN & Foreign National
Programs Zac focuses on
Licensing and contact
Licensing
Zac Cook, NMLS #2111496
Verify license states on NMLS Consumer Access(opens in a new tab)Cornerstone First Mortgage, LLC, NMLS #173855
Company record on NMLS Consumer Access(opens in a new tab)Cornerstone First Mortgage, LLC is an Equal Housing Opportunity Lender. See Disclosures & Licensing.
Profiles and reviews
Guides by Zac Cook
15 guides written by Zac on self-employed and alternative-documentation lending.
- Compare & DecideWhy One Lender's 'No' Isn't Final: How Non-QM Guidelines DifferNon-QM guidelines vary by investor: minimum FICO, lookback months, expense factors. Why one lender's decline isn't final and how in-house underwriting across 25+ investor programs works.
- How to QualifyBank Statement Loan Requirements: What You Need to QualifyBank statement loan requirements: 640+ FICO, 12 or 24 months of deposits, eligible property and occupancy types, and what underwriters look for in statements.
- Compare & DecideBroker vs. Direct Lender: What Self-Employed Borrowers Should KnowAn honest look at mortgage brokers vs. direct lenders for self-employed borrowers — plus the questions to ask before you choose.
- Who We HelpMortgages for Gig Workers and Side HustlersGig workers and side hustlers can qualify for a mortgage without a W-2 history. See the documentation paths that fit rideshare, freelance, and app-based income.
- Compare & DecideFlexible Qualifying vs. Bank Statement Loans: Choosing the Right PathNot sure whether flexible qualifying or a bank statement loan fits you better? Compare requirements, documentation, and occupancy to choose the right path.
- How to QualifyCan You Get a Mortgage Without Tax Returns? Yes — Here's HowYes, you can get a mortgage without tax returns — by qualifying with bank statements, 1099 forms, a CPA-prepared P&L, or your assets instead. Here's how.
- Compare & Decide12-Month vs. 24-Month Bank Statement Loans: Which Should You Choose?12-month vs. 24-month bank statement loans compared: how the deposit average is computed, when each lookback wins, and how seasonality changes the math.
- Who We HelpHome Loans for 1099 Contractors and Freelancers1099 contractors and freelancers can qualify for a mortgage with 1 to 2 years of 1099 forms instead of tax returns. How the program works and who it fits.
- Loan ProgramsAsset-Based Mortgages: Qualifying on Your Savings and InvestmentsAsset-based mortgages turn savings, investments and retirement balances into qualifying income. How investors discount assets, the math, and who it fits.
- Loan ProgramsBuying a Second Home or Investment Property Without Tax ReturnsHow self-employed buyers can purchase a second home or investment property using bank statement deposits instead of tax returns and business write-offs.
- Compare & DecideNon-QM vs. Conventional: When a Bank Statement Loan Makes More SenseNon-QM vs. conventional for self-employed borrowers: when a bank statement loan makes more sense than tax-return-based underwriting, with a full comparison.
- How to QualifyWhat Credit Score Do You Really Need for a Self-Employed Mortgage?What credit score you really need for a self-employed mortgage, from bank statement loans to flexible qualifying, and how each program's minimum works.
- Who We HelpBuying Your First Home While Self-Employed: What to ExpectWhat self-employed first-time homebuyers can expect: the documents you'll need, a realistic timeline, common surprises, and how to get matched to a program.
- How to QualifyQualifying With Both W-2 and Self-Employment IncomeHow households with both W-2 and self-employment income qualify for a mortgage — side businesses, mixed-income spouses, and co-borrower W-2 income.
- Loan ProgramsFinancing Non-Warrantable Condos and CondotelsWhat makes a condo non-warrantable, how condotels differ, and how non-QM financing handles both when the building — not the borrower — is the obstacle.
Non-QM loan programs. Alternative income documentation required. All loans subject to underwriting approval, income/asset verification, and ability-to-repay determination. Not all applicants will qualify. Program availability and guidelines subject to change without notice.