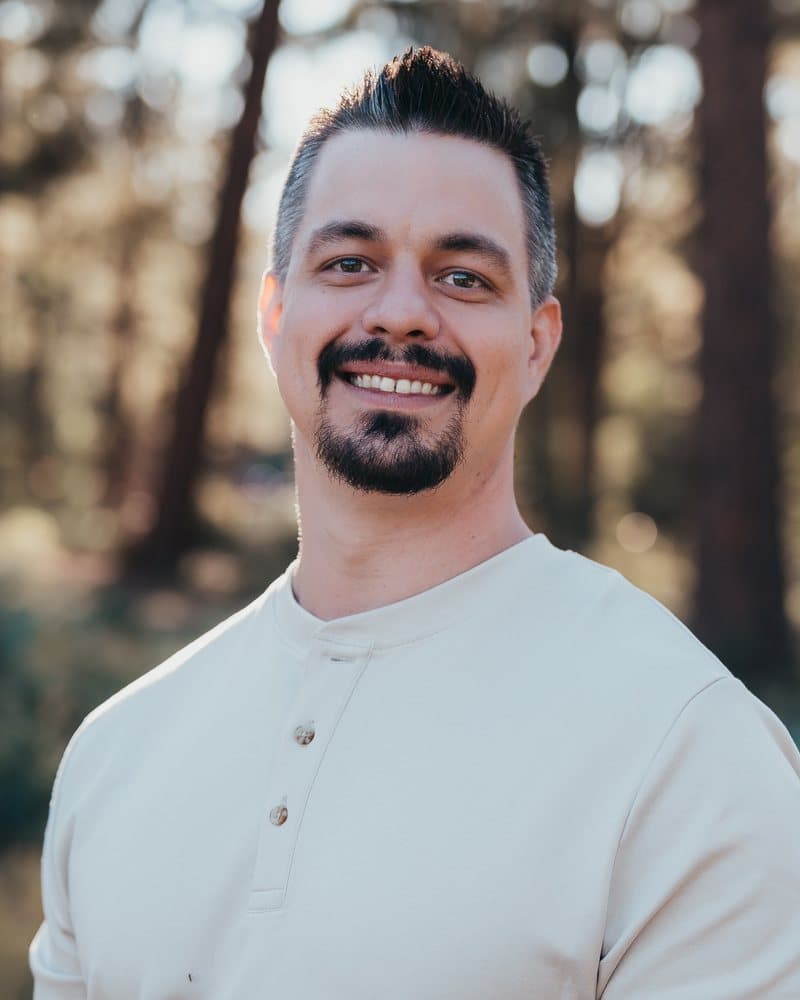
Tanner Cook
Mortgage Loan Originator · NMLS #2090424(opens in a new tab)
Cornerstone First Mortgage, LLC · NMLS #173855(opens in a new tab)
About Tanner
Tanner Cook is a mortgage loan originator (NMLS #2090424) at Cornerstone First Mortgage, LLC (NMLS #173855) and, with his brother Zac Cook, part of the Cook Brothers Mortgage Team. He focuses on bank statement (including the 3-month option with a P&L), 1099 and P&L-only loans for self-employed borrowers, plus WVOE loans for people paid by an employer they don't own.
Tanner specializes in self-employed and alternative-documentation lending. When tax returns understate what a business owner really earns, he structures the file around bank statements, a CPA-prepared P&L, or assets — and matches it to the investor whose guidelines actually fit.
Specialties
- Bank Statement Loans
- 1099 & Self-Employed Lending
- Complex Income Structuring
Programs Tanner focuses on
Licensing and contact
Licensing
Tanner Cook, NMLS #2090424
Verify license states on NMLS Consumer Access(opens in a new tab)Cornerstone First Mortgage, LLC, NMLS #173855
Company record on NMLS Consumer Access(opens in a new tab)Cornerstone First Mortgage, LLC is an Equal Housing Opportunity Lender. See Disclosures & Licensing.
Profiles and reviews
4.89 average from 45 reviews of Tanner Cook on Experience.com
Guides by Tanner Cook
18 guides written by Tanner on self-employed and alternative-documentation lending.
- Who We HelpMortgage for Content Creators: How Lenders Read Your IncomeCreator income from AdSense, Patreon, brand deals and PayPal lands messy. Here's how bank statement, 1099 and P&L loans read it, and what gets backed out.
- Who We HelpMortgage for Restaurant Owners: Bank Statement & P&L PathsBig deposits, thin margins. How restaurant, bar and café owners qualify with bank statement, CPA expense letter or P&L loans, and what trips up their files.
- Compare & DecideCompare Non-QM Loan Offers: Reading the Loan EstimateHow to compare non-QM loan offers line by line on the Loan Estimate: prepayment penalties, interest-only periods, ARM caps, fees, credits and reserves.
- Compare & DecideSelf-Employed Mortgage Options Compared (2026)Compare 8 non-QM mortgage programs side by side: the documents each uses, history needed, how income is figured, who it fits and the trade-offs.
- How to QualifyHow to Refinance When You're Self-Employed and Rates Have ChangedA step-by-step guide for self-employed borrowers refinancing after a rate shift, using bank statement, 1099, or asset-based documentation instead of tax returns
- Loan ProgramsWhat Is a Self-Employed Mortgage? A Complete GuideWhat is a self-employed mortgage? A complete guide to bank statement, 1099, P&L, WVOE, asset-based, ITIN, and foreign national loan programs in one place.
- Who We HelpHome Loans for Business Owners Who Write Off Most of Their IncomeHome loan options for business owners who write off most of their income: P&L-only, bank statement, and asset-based programs that look beyond your return.
- Loan ProgramsP&L-Only Loans: Qualifying With a CPA-Prepared Profit and Loss StatementLearn how a P&L-only mortgage lets self-employed borrowers qualify with a 12-month CPA-prepared profit and loss statement instead of tax returns and a 4506.
- How to QualifySelf-Employed Less Than Two Years? Your Mortgage OptionsSelf-employed less than two years? Compare the conventional two-year rule with non-QM options like 12-month bank statement and one-year 1099 loan programs.
- Loan ProgramsCash-Out Refinance Without Tax Returns: How Self-Employed Owners Tap EquityHow self-employed homeowners can cash-out refinance without tax returns — qualifying with bank statements, 1099s, or assets, plus how delayed financing works.
- Who We HelpHome Loans for Real Estate Agents and Commission-Based EarnersHow real estate agents and commission-based earners qualify for a mortgage using 1099s or bank statement deposits instead of tax returns and write-offs.
- How to QualifyHow Underwriters Calculate Your Income From Bank StatementsHow underwriters calculate self-employed income from bank statements: deposit windows, expense factors, and the math behind your qualifying monthly income.
- Loan ProgramsWVOE Loans: Qualifying With an Employment Verification Form Instead of PaystubsWVOE loans let eligible borrowers qualify with an employer-completed verification form instead of paystubs, W-2s, or tax returns. Here's how the program works.
- Who We HelpLLC and S-Corp Owners: How Your Business Structure Affects Your MortgageHow LLC and S-corp structures affect mortgage qualifying: pass-through income, salary vs. distributions, business bank statements, and closing in an LLC.
- How to QualifyHow to Prepare Your Bank Statements Before You ApplyHow to prepare your bank statements before a mortgage application: separate accounts, clean deposits, avoid unexplained transfers, and build a runway.
- How to QualifyThe Documents You Need for a Self-Employed MortgageA step-by-step checklist of the documents self-employed borrowers need for bank statement, 1099, P&L, and asset-based mortgage programs before applying.
- Compare & DecidePersonal vs. Business Bank Statements: Which Should You Use to Qualify?Personal or business bank statements can change your mortgage qualifying income. Compare the expense factors, scenarios, and math to decide which to use.
- Loan ProgramsITIN and Foreign National Home Loans: Buying Without a U.S. Credit HistoryITIN filers and foreign nationals can still buy U.S. property. Learn the two distinct loan paths for buyers without a Social Security number or U.S. credit.
Non-QM loan programs. Alternative income documentation required. All loans subject to underwriting approval, income/asset verification, and ability-to-repay determination. Not all applicants will qualify. Program availability and guidelines subject to change without notice.