You built your income.
We'll build the mortgage around it.

 Tanner & Zac Cook NMLS #2090424 / #2111496Cornerstone First Mortgage, LLC NMLS #1738554.89 · 45 reviews of Tanner Cook on Experience.com
Qualify with bank statements, 1099s, a P&L, or assets instead of tax returns.
Find the program that fits how you earn
Answer a few quick questions to see a likely path — no tax returns needed to start.
How do you earn?
When your tax returns don't tell the whole story
Write-offs shrink the taxable income that traditional underwriting reads on your returns. Alternative-documentation (non-QM) loans qualify you on how money actually moves through your business instead.
- Bank Statement Loans12 or 24 months of bank deposits
- 1099 Income LoansOne to two years of 1099s
- P&L-Only LoansA 12-month P&L from your CPA or tax preparer
- 3-Month Bank Statement + P&L3 months of statements plus a P&L from a licensed tax professional
- WVOE LoansA verification form your employer completes
- Asset-Based LoansEligible assets converted to qualifying income
- Flexible QualifyingReduced documentation; ability to repay still assessed
- ITIN LoansFor ITIN tax filers without a Social Security number
- Foreign National LoansFor buyers with no U.S. credit, green card or SSN
Non-QM loan programs. Alternative income documentation required. All loans subject to underwriting approval, income/asset verification, and ability-to-repay determination. Not all applicants will qualify. Program availability and guidelines subject to change without notice.
Guides
All guides- What Is a Self-Employed Mortgage? A Complete Guide
- Can You Get a Mortgage Without Tax Returns? Yes — Here's How
- Self-Employed Mortgage Options Compared (2026)
- Bank Statement Loan Requirements: What You Need to Qualify
- How Underwriters Calculate Your Income From Bank Statements
- 12-Month vs. 24-Month Bank Statement Loans: Which Should You Choose?
Buying in Arizona, our home market? Bank statement loans in Arizona
Four steps, built around your income
No stacks of tax returns. Just a clear path from how you earn to the keys.
- Step 1
Tell us how you earn
A 60-second quiz on how you make your money and how you would prefer to document it.
- Step 2
We match for guideline fit
One application, checked in-house against 25+ non-QM investor programs to find the guidelines that fit your situation.
- Step 3
We price the fit
We compare pricing where more than one program fits, then run your file against that program’s guidelines, with underwriting done in-house.
- Step 4
Clear to close
We coordinate verification, appraisal, and underwriting through to a clear-to-close.
Two brothers. One file. 25+ investor programs, underwritten in-house.
Tanner and Zac Cook work your file with you from the first call, matching how you earn to a program whose guidelines allow it. Cornerstone First Mortgage, LLC (NMLS #173855) underwrites in-house to the guidelines of 25+ non-QM investors and runs your file against the program it fits before you apply. Tanner and Zac stay your point of contact from start to finish.
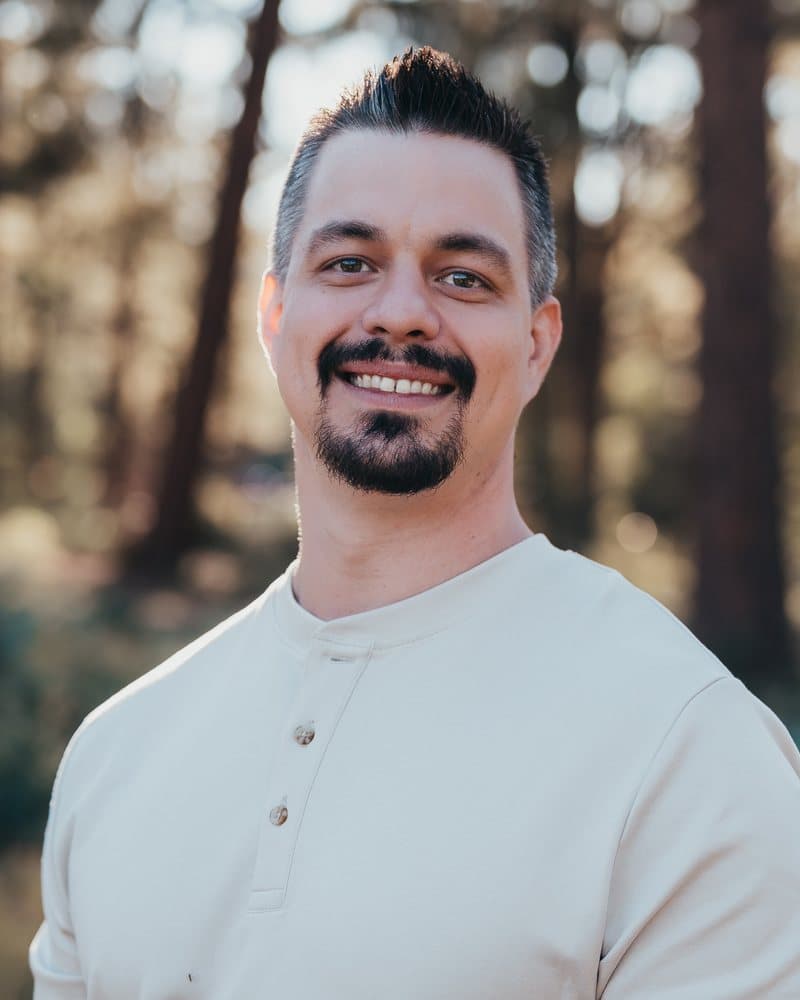
Tanner Cook
Mortgage Loan Originator
Tanner specializes in self-employed and alternative-documentation lending. When tax returns understate what a business owner really earns, he structures the file around bank statements, a CPA-prepared P&L, or assets — and matches it to the investor whose guidelines actually fit.
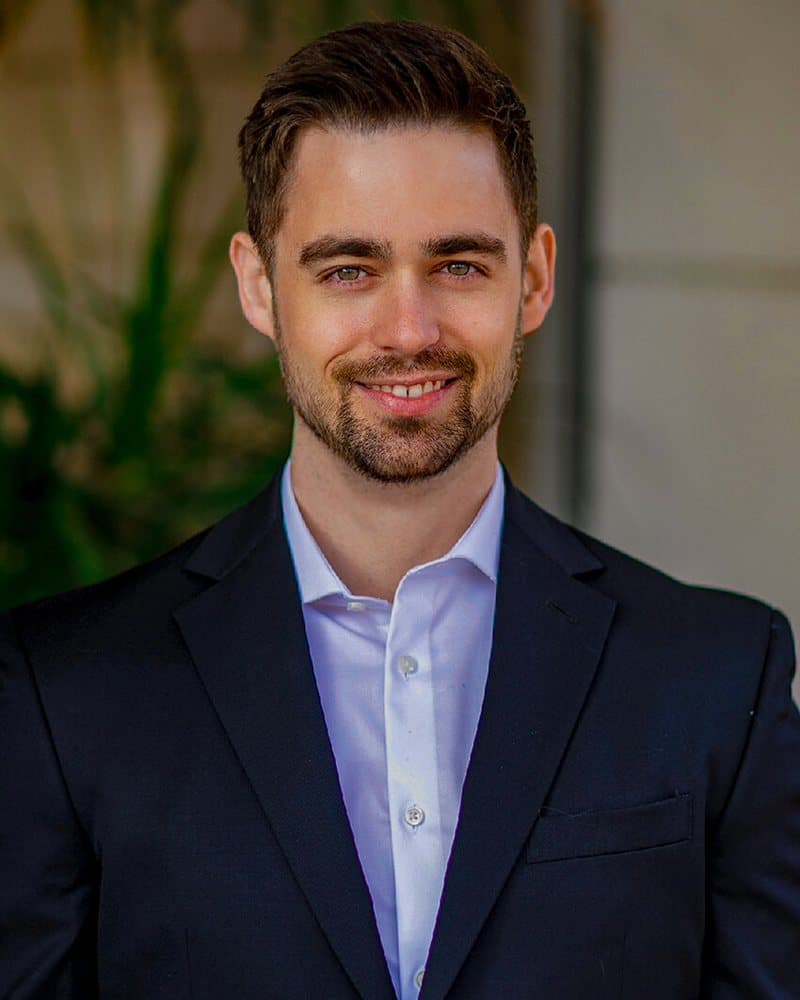
Zac Cook
Mortgage Loan Originator
Zac works with entrepreneurs, investors, and international buyers. He checks every file against the non-QM programs Cornerstone can offer in the borrower’s state, looking for a guideline that fits — from asset-based qualification to ITIN and foreign national programs.
Real clients. Real closings.
Reviews from clients and partners who worked with the Cook Brothers.
4.89 · 45 reviews of Tanner Cook on Experience.comSelf-employed mortgage FAQs
Honest answers to what business owners, contractors, and investors ask us most.
Yes. Non-QM programs let self-employed borrowers qualify with alternative documentation instead of tax returns — an average of 12 or 24 months of bank statements (or 3 months of statements paired with a P&L from a licensed tax professional), one to two years of 1099s, a CPA-prepared profit & loss statement, or liquid assets. Every loan is still subject to underwriting and an ability-to-repay determination.
Underwriters average your deposits over 12 or 24 months. On business bank statements an expense factor (commonly 50%) is applied to reflect business costs; personal statements are typically treated differently. Your loan officer reviews your statements to estimate qualifying income before you formally apply, so there are no surprises.
Minimums vary by program. Bank statement loans start at a 640 credit score; most other alternative-documentation programs start at 660, and flexible qualifying starts at 680. Higher scores generally open access to higher loan amounts and loan-to-value ratios.
Loan amounts run up to $5M on bank statement loans and up to $3M on 1099, P&L, and asset-based programs, depending on your credit, equity, and the property. How much you can borrow against the home’s value depends on the program, your credit and the loan size, and it steps down as loan amounts rise. Guidelines are subject to change without notice.
Not always. Some programs allow a smaller down payment at lower loan amounts. Requirements increase with loan size and vary by program and credit profile — we confirm the specifics for your file at application.
Many programs look for a two-year self-employment history, but some allow as little as one year. Tell us your timeline in the quiz and we will match you to the investors whose guidelines fit your situation.
Yes. Asset-based qualification turns eligible assets (checking, savings, stocks, bonds and retirement accounts) into qualifying income: each account is counted at the share the investor allows, the funds you need to close and any required reserves are subtracted, and what remains is divided by the investor’s set number of months (often 60). No employment is required. This program is available for primary residences.
Yes. 1099 income loans let contractors, freelancers, and gig workers qualify using one to two years of 1099s, with no tax returns or 4506 required.
Yes. ITIN loans serve borrowers who file taxes with an ITIN instead of a Social Security number, and foreign national loans finance non-US buyers with no US credit history or green card. Both qualify through alternative documentation.
Yes. Every program requires documentation — bank statements, 1099s, a P&L, or asset records — and every loan includes a full ability-to-repay determination under federal rules. We simply use documentation other than tax returns; we never rely on an unverified income figure.
Cornerstone First Mortgage, LLC (NMLS #173855) is licensed to originate residential mortgage loans in many states, but not every state. Our Disclosures & Licensing page lists each state license Cornerstone publishes, NMLS Consumer Access shows the official record, and we confirm that we can finance a home in your property's state before you apply. We do not offer, solicit, or provide mortgage services to New York residents or for properties located in New York. If you are a New York resident, we may, at your request, refer you to a licensed mortgage provider; we do not receive any fee or compensation for such a referral.
We take one application and check it in-house against the guidelines of 25+ non-QM investors, matching your income structure to a program that allows it and comparing pricing when more than one fits. Because Cornerstone underwrites in-house, your file is run against that program’s guidelines before you apply, so issues surface up front.
Still have questions? Talk it through with Tanner or Zac — no application required. (469) 405-2690
Let's build the mortgage around your income.
Take the 60-second quiz and we'll match how you earn to the investor whose guidelines fit — no tax returns required.
Prefer a scheduled call? Book with Tanner · Book with Zac